Showing posts with label bailout. Show all posts

11/01/2015

Greek banks face $15.9b bill after economic debacle


Πηγή: AFRWeekend
1 Nov 2015

Greece's four main banks must raise €14.4 billion in fresh capital, the European Central Bank said, as investors and taxpayers face the cost of repairing the damage from six months of wrangling between the nation's government and its creditors.

An asset-quality review carried out by the ECB resulted in valuation adjustments of €9.2 billion for the National Bank of Greece SA, Piraeus Bank SA, Eurobank Ergasias SA and Alpha Bank AE, the Frankfurt-based supervisor said Saturday in a statement.

The banks' capital gap amounted to €14.4 billion under a simulated stress test scenario, and €4.4 billion under baseline macroeconomic assumptions. The four banks will have to submit recapitalization plans to the ECB's supervisory arm by November 6.

"Covering the shortfalls by raising capital would then result in the creation of prudential buffers in the four Greek banks, which will facilitate their capacity to address potential adverse macroeconomic shocks," the ECB said in the statement, adding that a minimum of €4.4 billion, corresponding to the AQR and baseline shortfall, is expected to be covered by private means.

The capital shortfall is "significantly lower than feared," German Deputy Finance Minister Jens Spahn said, while US undersecretary for international affairs Nathan Sheets said in an interview before the results that the health of the Greek financial system is now "clearly better" than a few months ago.

National Bank of Greece, the country's biggest bank by assets, has a total capital shortfall of €4.6 billion, including €1.6 billion from the baseline scenario.

Piraeus has the biggest shortfall of all the lenders, and needs to raise €2.2 billion under the baseline scenario, and €4.9 billion in total.

Piraeus reported on Saturday a net loss of €635 million in the first nine months of the year and an accelerating pace in the formation of sour loans.

Alpha Bank only needs to raise €263 million under the baseline scenario, out of a total shortfall of €2.7 billion.

Eurobank has the lowest aggregate shortfall, totaling €2.2 billion, with €339 million corresponding to the baseline scenario.

Attica Bank has a shortfall of €857 million in the baseline scenario and €1 billion in the adverse scenario, according to a separate comprehensive assessment conducted for the small lender by the Athens-based central bank.

"Alpha expectedly fared best and Piraeus expectedly fared worst," Paris Mantzavras, analyst at Athens-based Pantelakis Securities wrote in a note to clients after the publication of the results.

"Compared to our market estimates for the total capital bill, Eurobank is a positive surprise and National Bank a negative one."

The European Commission said in a statement that it is "encouraged" by the results, while Eurobank's Chief Executive Officer Fokion Karavias said that the lender's capital needs under the stress test's adverse scenario are "fully manageable."

Alpha Bank, in a filing to the stock exchange, said the result "demonstrates resilience," despite "higher hurdle rates and the repayment of €940 million of state preference shares in 2014, which further improved the quality of capital."

BAIL-OUT AGREEMENT

The government of Prime Minister Alexis Tsipras and Greece's European creditors reached a bail-out agreement this summer after months of wrangling that brought the country to the brink of leaving the currency union and resulted in capital controls.

Recapitalizing the country's lenders, after a month- long forced shutdown in July and record deposit bleeding, is the first step to restart the country's economy, which is still crippled by restrictions on transfers of capital and ATM withdrawals.

Lenders will ask their shareholders and bondholders to voluntarily offer to plug any holes identified by the ECB, before resorting to a €25 billion state backstop, according to a bank recapitalization bill which the Greek Parliament approved on Saturday. Taxpayers' funds will come from euro-area emergency loans under Greece's latest bailout agreement.

Common and preferred stock as well as other financing instruments, including unsecured senior liabilities, can be bailed in before a financial institution is eligible to use the public backstop of the state-owned recapitalization fund to cover its shortfall, according to the bill. Eurobank, Alpha Bank, and Piraeus have already extended swap offers to their bondholders, as they seek to reduce liabilities and boost their capital.

A spokesman for the European Stability Mechanism-- the currency union's crisis loans fund -- said that Greece can "quickly" use €10 billion,which have been mobilized for Greek bank recapitalizations and are currently sitting in a segregated account. With sufficient private-sector participation, the remaining €15 billion, which have been earmarked for capital injections under the terms of the bailout, will not be needed, the spokesman added, asking not to be named in line with policy.

This will also mean that Greece may not use the full €86 billion envisaged back in July.

"Capital shortfalls under the baseline scenario, which may be further reduced by the currently ongoing liability management exercises by the Greek banks and the restructuring plans to be submitted to the ECB, are manageable," analysts at Athens-based Euroxx Securities Vangelis Karanikas and Yiannis Sinapis wrote in a note to clients.

"All Greek banks should be able to cover the AQR and baseline needs through the private sector."

RECAPITALIZATION TERMS

The new recapitalization legislation empowers the state- owned Hellenic Financial Stability Fund to regularly evaluate the management and boards of Greek lenders that seek state aid.

Board members in Greek banks must have 10 years of international banking or finance experience, of which three years as board members.

At least one board member should have five years or more experience in bad loans management, and three independent board members, who will be presiding over all committees, mustn't have worked in a Greece-based bank during the past 10 years.

Officials who have served in senior political or public- sector posts over the past five years are banned from being appointed board members.

No bonuses will be distributed while a lender receives state aid and salaries of management are capped at the level of the annual compensation of the governor of the Bank of Greece, according to the legislation.

With assets totaling €296 billion at the end of June, the four banks tested by the ECB account for about 90 percent of the assets of credit institutions in Greece, the ECB said.

Attica Bank, which isn't considered a systemically significant lender, was assessed by the Bank of Greece, which identified a €1 billion shortfall.

The recapitalization bill which was approved Saturday allows HFSF to participate in capital raising actions of smaller banks and not just the four biggest ones.

"The shortfall number was in line with our expectation," Jonas Floriani, a London-based analyst with Keefe, Bruyette & Woods, said in an e-mail.

"The key now will be the capital plans and the recap framework."


10/30/2015

Greece’s Bailout Deal with Europe Is Starting to Show Cracks


Πηγή: FP
By David Francis
27 Oct 2015

The European Union’s agreement to provide Greece with the 86 billion euros, or $95 billion, bailout that Athens needs to stay solvent is beginning to show signs of strain, with creditors threatening to delay an October payment as Greek Prime Minister Alexis Tsipras struggles to implement promised austerity reforms.

On Monday, Valdis Dombrovskis, a senior European Commission official charged with assessing how well Greece is abiding by its August commitments, said that the EU and Greece still disagree on how to toughen foreclosure laws. Right now, an estimated 320,000 Greeks are in arrears, or behind in their home loan payments. This represents about 40 percent of all Greek home loans.

Tsipras’ government wants cover for borrowers with homes worth up to 300,000 euros, or $331,185, and who earn up to 35,000 euros, or $38,638 per year. That would account for about 75 percent of the loans now in arrears. According to the leftist Greek government, the EU’s counterproposal — protection for homes worth up to just 120,000 euros, or $132,474 — would leave 80 percent of the Greek borrowers who are behind on home payments at risk of losing their homes to foreclosure.

The growing foreclosure rift is the latest to strain the deal between Greece and its creditors: the European Commission, the European Central Bank, and the European Stability Mechanism, the fund created to keep stumbling European nations afloat. According to a Tuesday report in the German newspaper Süddeutsche Zeitung, Tsipras has followed through on only 14 of the 48 reforms he promised for a third, 86 billion euro, or $95 billion, bailout he agreed to in August. The paper also reported that Athen’s European creditors plan to hold back an October payment of $3.32 billion.

In August, Tsipras agreed to a host of changes, including reforming Greek labor markets, raising taxes, putting state assets up for sale, making spending cuts, and making changes to Greece’s generous pension system, like raising the retirement age. So far, he’s managed to push through bills on a property tax and punishments for early retirement, but he’s failed to put in place taxes on private school tuition or to begin privatizing Greek ports.

“There is growing concern in Berlin and among other creditors that reforms are already beginning to slide in Athens,” Mujtaba Rahman, head of the Eurasia Group’s European practice, said Tuesday. “This was expected next year, but the fact it is happening now is an indication of just how challenging the situation remains with Greece.”

The German newspaper’s report came as Dombrovskis acknowledged the foreclosure impasse and warned Tsipras’s leftist Syriza party to speed up the reform process. “There is no time to lose. There is a need to work very actively to modernize the Greek state and economy,” Dombrovskis said Monday.

Perhaps even more pressing is a planned 25 billion euro bailout payment to recapitalize Greek banks, which are badly in need of cash after extended closures, daily cash withdrawal limits, and emergency measures designed to keep money in Greece this past summer. This, too, depends on whether Greece can deliver the tax increase and privatization of public assets its government agreed to.

Looming over all of this is the International Monetary Fund. The IMF said it would not participate in the bailout unless Greece, plagued by years of anemic economic growth and unemployment at 25 percent, delivers the reforms it has promised; IMF officials are currently in Greece reviewing its progress. IMF chief Christine Lagarde wants some of Greece’s debt to be forgiven, something Germany says is illegal. Lawmakers in Berlin havewarned they might not participate in future bailouts without the IMF on board.

Tsipras’ failure to deliver reforms in a timely fashion is raising particular worry in the German capital. A summer standoff between the Greek prime minister and Berlin, which saw Tsipras and the Greek people reject an austerity deal in July only to accept harsher reforms in August, left many, including German Finance Minister Wolfgang Schäuble, concerned that the government in Athens would not follow through on what it has promised. Germany is the largest contributor to the bailout fund.


2/25/2014

Christine Lagarde thinks the troika got it wrong on Greece? If only she knew

Christine Lagarde claimed that the IMF, the EC and the ECB had ‘made sure there was enough of a safety net so that people who were most exposed would not suffer too much'
Πηγή: The Guardian
By Alex Andreou
Feb 24 2014

On Thursday, Christine Lagarde made some comments in an interview for Australia's ABC which have passed largely unreported, Greece no longer being the crisis en vogue. She admitted that the troika – the entity consisting of the European commission, the European Central Bank and the International Monetary Fund, of which Lagarde is the head – was mistaken in its calculations initially and that this led to the wrong economic solutions being applied to the Greek crisis. She claimed, nevertheless, that they had "made sure there was enough of a safety net so that people who were most exposed would not suffer too much".

I don't know what Lagarde sees when she visits Greece. Perhaps it is a different country to the one I experience whenever I travel back. After all, for someone on a cool, tax-free $500,000 salary, who no doubt flies first class and is transferred by limousine between five-star hotels and clean, white marble conference buildings, reality may be easy to miss.

Or perhaps there is another, first-class reality, a five-star version of events. Such a visitor is unlikely to see the old women clad in black dresses and scarves, who appear like an ancient Greek chorus as soon as supermarkets have rolled down their shutters, in order to search through the bins for scraps in the evening gloom. Or the thousands queueing up every day for care packages from Médecins du Monde, or the addicts shooting up in the streets, or the body bags of families being wheeled out of flats, suffocated as they burned rubbish in their stove to keep warm. In my own small town of Mykonos – largely insulated by virtue of its popularity as a holiday destination – two people tried to kill themselves last week, due to financial ruin.

On Friday the respected medical journal the Lancet published a report which told quite a different story to that offered by the head of the IMF. It set out the devastating effect austerity has had on the health of the nation. It explained how the drastic reduction in healthcare and social spending combined with the pressure of a higher tax burden, unemployment of nearly 25% and an economy which has shrunk more than 20% in the last few years to create a pincer movement which has caught millions of innocent people in its grip.

It has resulted in 800,000 people with no health coverage, escalations in HIV infection, suicide rates, infant mortality, child abandonment, deaths related to violence and ill health from poor nutrition. All the data were corroborated, and have even deteriorated since being collated for the report.

"In view of this detailed body of evidence for the harmful effects of austerity on health, the failure of public recognition of the issue by successive Greek governments and international agencies is remarkable. Indeed, the predominant response has been denial that any serious difficulties exist", the Lancet report concludes. "This dismissal meets the criteria for denialism, which refuses to acknowledge, and indeed attempts to discredit, scientific research."

It is the essence of such denialism which Lagarde exhibits when she says Greece is out of the woods and praises the country for reportedly achieving a primary surplus of more than €1.5bn – a giant amount for such a small economy. This surplus is in itself the subject of very lively debate, with many suggesting it is the result of the same creative accounting techniques that got the country's economy into trouble to begin with.

This denial is accompanied by a monumental crassness; a lack of even the most rudimentary understanding of Greece's collective psyche, its people and its history. How else can one explain Lagarde saying that "we can only celebrate now the fact Greece is finally coming out with a primary surplus, as we call it, which hasn't happened since 1943"?

In 1943 Greece was in the middle of a four-year occupation by Nazi Germany, a period during which the country mourned nearly 10% of its population; the victims of violence, execution, disease and hunger. The Great Famine of Athens alone resulted in an estimated 300,000 deaths in the winter of 1942. It's good to know, however, that the country's books were balanced.

Are such comments the result of gargantuan thoughtlessness – or do they hide a deeper, uglier message, that Greece does best under foreign rule? One thing is certain: that tragically they play directly into the hands of fascist organisations like Golden Dawn, with its not-really-a-swastika logo, not-really-nazi salute and not-really-criminal parliamentarians. Their central message is one of suffering Hellenism under an economic occupation. Their central promise, to rid Greece of foreign interference. Recent opinion polls have them comfortably in third position. Every time Christine Lagarde decides to comment on Greece, they must cheer.


2/24/2014

Greece in banking sector stand-off with bailout lenders


Πηγή: FT
By Peter Spiegel and Kerin Hope
Feb 24 2014

The Greek government and its bailout lenders are locked in a new stand-off over the health of Greece’s banking sector, with Athens contending its financial system requires less than €6bn of new capital, while international monitors insist it needs at least three times that amount.

The €6bn estimate was calculated by the Greek central bank after a long-awaited private analysis by BlackRock and was provided to monitors from the so-called “troika” of international lenders, ahead of their arrival in Athens on Monday to resume talks over their latest review of the bailout programme.

The review, the most contentious in more than a year, was to be completed in September, but troika officials say less than half of the economic reform commitments made by the Greek government have been completed. Their return to Athens on Monday is their first visit in two months.

The dispute over banks’ recapitalisation needs risks adding a new, potentially explosive point of contention between the two sides, as it will have a direct effect on whether Athens will require a third international bailout when the remaining €10.1bn in EU funding in the current €172bn rescue runs out later this year.

The Greek government had hoped to tap an estimated €10bn in bailout cash remaining in its bank rescue fund to pay for other government expenses as part of a strategy to avoid a third bailout. The International Monetary Fund last year estimated the current bailout is nearly €15bn short of cash over the next two years.

If Athens must use all remaining cash in the bank rescue fund to recapitalise its financial system, it will be required to fill the financing gap with new bailout money, necessitating a third rescue.

According to senior troika officials, the dispute has become so contentious that the IMF has threatened to publish its own estimates of banking sector needs – which are close to €20bn – if Athens proceeds with the €6bn figure.

The European Central Bank, which officials say has similar estimates to the IMF, has also pushed for Greece to take a closer look at its conclusions. The ECB, which takes over as the EU’s bank supervisor later this year, is concerned Greece’s bank evaluation matches up with its highly anticipated eurozone-wide review before the year is out.

Greece struggles on with drastic austerity as eurozone leaders continue to argue over how to help the country cope with its debt mountain

“The ECB needs a significant number to signal that its comprehensive bank assessment later this year will not be a walkover,” said Mujtaba Rahman, head of European analysis at the Eurasia Group risk consultancy. “But there’s only limited cash left in the [bailout] envelope, and parliaments certainly won’t be committing any new money ahead of May’s European elections.”

One Greek banker briefed on the dispute said the government’s estimate is based on banks returning to profit next year, but troika officials believe that scenario is overly optimistic, particularly given the rapidly increasing rate of non-performing loans.

If prolonged, the dispute will undermine Greece’s chances of turning the economy around this year as banks are stalling on extending new loans to stimulate growth until the recapitalisation is completed. The government has already postponed legislation to privatise Eurobank, the fourth-largest lender, because of the dispute.

Eurobank says it has lined up nearly €2.5bn in funding to cover its capital needs, mainly from foreign investors, in what it hopes will be a flagship deal showing Greece is on the road to recovery. It had hoped to wrap up a deal by April.

The Greek central bank has said the result of the BlackRock stress tests will be announced at the end of the month, a three month delay from its original plan. Part of the delay was due to the central bank’s decision to call in NM Rothschild and Ernst & Young to provide second and third opinions.

If the recap dispute is not resolved during this round of troika negotiations in Athens, the BlackRock exercise may be set aside, leaving it to be resolved by the ECB’s own stress test, a finance ministry official said.

“It makes sense for the European regulator to sort this out,” said another Greek bank executive. “Why should Greek banks be handled any differently from others in Europe?”

Such a scenario is unlikely to be welcomed by the troika, particularly the IMF, which requires a year’s financing to be in place before it can distribute any additional bailout funding. Without a decision on total recapitalisation needs and a third programme, the IMF is likely to be forced to withhold future payments.


9/11/2013

‘One or Two More’ Greece Bailouts Likely

Experts from supervising bodies will meet for debt recovery talks in Athens later this month.
Πηγή: Time
By Sophie Brown
Sept 11 2013

The eurozone may need to help Greece with one or even two more aid packages, according to a representative of the European Central Bank (ECB).

“We will have to make some extra efforts — certainly once, perhaps twice”, said Luc Coene, a ECB Governing Council member on Wednesday.

Greece’s economy is seeing “very slow” improvements, he said, following a €200 billion ($265 billion) bailout from eurozone lenders and another €40 billion ($530 billion) package from the International Monetary Fund. But the country’s debt problems no longer pose an immediate threat to the “whole edifice” of the eurozone.

The financial situation is “much better armed” to ward off another crisis, said Coene, who is also the president of Belgium’s National Bank. International experts from the European Commission, European Central Bank and International Monetary Fund will meet in Athens later this month for talks on Greece’s recovery.

7/13/2013

New aid gives Greece summer respite before showdown

Athens' municipal employees take part in a protest outside the town hall of Athens July 10, 2013.
Πηγή: Reuters
By Deepa Babington
July 11 2013

Greece has scraped through its biggest political and financial challenge this year by securing a tranche of aid from international lenders but the reprieve may only be temporary.

Crunch time for Athens will come at the end of September when EU and IMF inspectors are expected to return to discuss how to plug a budget gap for 2015 and 2016, raising the specter of more austerity cuts that may spark a new political crisis.

Even if it survives that, Greece will still need more debt relief from the euro zone before it can get back on its feet.

On Monday the lenders approved 6.8 billion euros from an emergency bailout put together in 2012 to keep the economy afloat and prevent a deepening of the regional debt crisis.

The money spares Greece from defaulting on its debt in August and tides it over until after elections in Germany in September.

But Greece will only get the full amount if the coalition government led by Prime Minister Antonis Samaras speeds up reforms to get them back on the agreed schedule.

"It's certainly going to get tougher both economically and politically," said Fredrik Erixon, director of the European Centre for International PoliticalEconomy in Brussels.

"They're kicking the issue a couple of months into the future ... we're going to continue with this charade between the troika and the government where everyone knows what's going on - that it's entirely unrealistic for Greece to live up to its expectations, both in the short and long term."

TALK OF "GREEKOVERY"

After nearly crashing out of the euro last year, Greece's debt crisis appeared to have largely abated this year and Samaras had even started to talk about a nascent "Greekovery".

But the seven-month lull came to an abrupt end last month when the government nearly collapsed over the closure of its state broadcaster and 10-year bond yields shot up to over 11 percent from the single digit levels seen earlier this year.

The latest bailout review then showed that after three years and 200 billion euros in aid Greece remains in trouble. Public sector reforms are elusive, tax collection is anemic, and debt is set to top 175 percent of gross domestic product this year.

Even if Greece can get through its next review, it faces a financing gap that is only likely to be resolved by additional debt relief, this time borne by euro zone states long fed up of Greece's seemingly unending funding needs and failure to reform.

Complicating matters further, the IMF increasingly faces a questions over whether it can keep supporting a program that may not bring Greece's debt down to a sustainable level.

With European paymaster Germany unwilling to risk a flare-up in the euro zone crisis before a national election, Greece faces its next major test in September when it must outline savings worth 4 billion euros to bridge a fiscal gap in 2015 and 2016.

Trying to plug it with more austerity could mean the end for Samaras's shaky two-party coalition, which already lost a junior ally in June when he tried to meet public sector layoff targets by shutting the state broadcaster ERT and firing 2,600 staff.

"CAN'T TAKE ANY MORE"

Samaras has already ruled out any further austerity measures for a nation faced with a 27 percent jobless rate and the Socialist PASOK party - his only remaining ally - has made it clear it will not support another round of painful cuts.

"The economy and society can't take any more measures," a PASOK official said was the main message to the EU and IMF.

Previously agreed austerity plans are already showing the strains in Greece - municipal workers have called a series of strikes while ERT workers have mounted a successful legal appeal and continue to broadcast from their occupied headquarters.

With just a five-seat majority in parliament, Samaras will find it difficult to find a way to plug the budget hole while keeping his coalition intact, analysts say.

"The flexibility of introducing additional austerity measures over and above those in the current program would be an extremely difficult task for the government given the state of the economy and unemployment," said Platon Monokroussos, an economist at Eurobank.

Instead of socially explosive layoffs or wage and pension cuts, the government could try and bridge the gap by extending special taxes and levies when they expire or through higher revenues from tax collection, though whether that will be enough to convince the troika remains to be seen.

If the government survives that review without a fresh crisis, the focus will shift to closing the year with a primary surplus before interest payments. This would qualify Greece to seek further debt relief, which the IMF has been pushing for but the euro zone wants to avoid discussing until spring 2014.

DOUBTS ABOUT THE FUTURE

After a restructuring last year of privately-held debt, over 90 percent of Greece's outstanding public debt of about 300 billion euros is in the hands of official creditors, mainly euro zone states and the European Central Bank.

Many economists believe restructuring that debt is inevitable to make the numbers add up over the long term, not least because Greece's economy has consistently missed growth projections, and few believe there is any other way to bring debt to below the 120 percent of GDP target level by 2021.

"From the Greek side, tidying up fiscally is not enough, structural changes in the economy are needed," said Nikos Vettas, chief of Greek think tank IOBE.

"From the part of creditors, action is needed so that the debt problem does not become a brake on growth - in other words relief commensurate to the course of reforms."

In addition, funding from Greece's bailout ends in 2014, but Athens' assertion that it could start tapping the bond markets from next year to tackle its future funding needs have appeared premature since yields soared in June.

The IMF - which does not expect Greece to return to markets before the end of 2016 - estimates Greece could face a funding gap of between 5.5 and 9.5 billion euros over 2015-2016.

Greece has relatively modest levels of debt maturing after 2014 - less than 10 billion euros annually until over 60 billion euros of debt comes due in 2042 so a small amount of debt relief to extend maturities could make a big difference.

But given Greece's history of failed reform efforts and missed targets there are many doubts about the future.

"What has the country really achieved? Fiscal adjustment and a reduction in labor costs. What they haven't achieved is structural reform across the board," an EU official said.

Even with reforms and economic growth, Greece may have to stay under a bailout program for longer than currently foreseen, the official said.


7/03/2013

UPDATE 1-Greece to miss public sector reform goal-officials


Πηγή: Reuters
By Lefteris Papadimas
July 3 2013

Greece cannot meet targets on reforming its public sector but expects to reach agreement with its foreign lenders on all other issues by Monday's Eurogroup meeting, finance ministry officials said on Wednesday.

Greece's EU and IMF lenders, unhappy with the progress it has made in reforming its bloated public sector, have given Athens a three-day ultimatum to convince them by Friday that it can deliver on its promises before unlocking 8.1 billion euros in aid.

Athens has already missed a June deadline to place 12,500 state workers into a "mobility scheme", under which they are transferred or laid off within a year, and officials said it would not be able to strike a deal on it by Monday.

"There is no chance that we will satisfy the current demands as they are set out," a senior finance ministry official said.

Athens needs to conclude talks with its lenders by the middle of the month to ensure it receives the latest aid tranche, which it needs to redeem about 2.2 billion euros of bonds in August.

Officials sought to play down fears of what would happen if Greece did not receive aid payments in time, saying in a "worst-case scenario" it could compensate by issuing additional treasury bills.

"It won't be the end of the world," said a second finance ministry official, who spoke on condition of anonymity.

"In the worst case scenario we will have to increase the issuance of T-bills, we will delay repaying arrears and it could lead to further delays to payments."

Finance Minister Yannis Stournaras was due to hold a third round of talks in as many days with inspectors from the "troika" of EU, IMF and ECB lenders at 1600 GMT.

To pressure Athens to deliver on reforms without creating a full-blown crisis, its lenders might refuse to pay the full sum in one go and break it up into monthly payments instead.

Public sector layoffs are an incendiary issue in Greece, which is struggling through a sixth year of recession, record high unemployment and sinking living standards.

Delays in pushing ahead with the hugely unpopular reforms has become a thorny issue in talks with the troika, which returned on Monday after a two-week break during which Prime Minister Antonis Samaras lost an ally in his ruling coalition and reshuffled his cabinet.

Kyriakos Mitsotakis, the newly-appointed administrative reform minister tasked with making the civil service smaller and more efficient, said he needed "several months" to get the scheme right.

"Clearly this cannot happen in a few days or a few weeks," Mitsotakis told Skai TV late on Tuesday.

He proposed compensating for the shortfall by speeding up firings of civil servants who have been found to have broken the law or those who were hired under false credentials.

Other sticking points in Athens's negotiations with its lenders include an unpopular property tax and a possible reduction in a sales tax for restaurants.

The government also plans to ask its creditors to lower this year's privatisation target of 2.6 billion euros after failing to find a buyer for natural gas company DEPA.

Still, officials were hopeful of a positive outcome at Monday's Eurogroup meeting.

"A favourable assessment of Greece at Monday's Eurogroup is to everyone's benefit," the finance ministry official said.


6/27/2013

Is Greece’s bailout running out of cash?


Πηγή: FT
By Peter Spiegel
June 26 2013

Just how off track is Greece’s €172bn second bailout? When the FT reported that a new €3bn-€4bn financing gap had opened up in the programme, EU and International Monetary Fund officials went out of their way to insist there wasn’t a gap at all.

“There is no financial gap. The programme is fully financed for at least another year, so there is no problem, on the premise that we reach a final agreement on the review in July,” said Jeroen Dijsselbloem, the Dutch finance minister who chairs the eurogroup.

IMF spokesman Gerry Rice weighed in with a written statement: “If the review is concluded by the end of July 2013, as expected, no financing problems will arise because the program is financed till end-July 2014.”

Notice the caveats, however. Both Dijsselbleom and Rice say there won’t be a shortfall – as long as the IMF is able to distribute its next €1.8bn aid tranche before the end of July. Why? Because of the new financing gap, which means the Greek programme essentially runs out of money in July 2014. The IMF must have certainty that Greece is fully financed for 12 months or it can’t release its cash, so after July, it must suspend its payments.

Lest any doubt remain, let’s turn to the European Commission and IMF reports on Greece, which make this abundantly clear. When the second bailout programme began early last year, the European Commission’s initial report contained a chart showing projected quarter-by-quarter aid payments that looked like this:


In the latest review, issued earlier this month, the same chart looked like this:


Notice the difference? In the third and fourth quarters of 2014, the €2.3bn in EU aid payments in the original bailout schedule are now €0. Instead, to fill the recent gaps, much of that cash had to be brought forward. Check out the EU payments for the current quarter, for instance. What was originally supposed to be a €3.2bn tranche became a €10.3bn disbursement.

What that means is a Greek programme that is fast running out of cash. In a press release issued Tuesday, the eurozone’s rescue fund said it had disbursed €130.6bn of the total €144.6bn in EU cash committed. So just €14bn left.

Which is why every little bit now counts. The €3bn-€4bn lost through slippage in Greece’s privatisation programme and the failure of several national central banks to roll over their Greek bond holdings may not sound like a lot, but each euro lost brings the day of reckoning that much closer.

So even if Greece dodges the current bullet and all aid payments are disbursed in July, the issue will come back again next quarter when the IMF’s 12-month window no longer exists. Still in doubt? Don’t take our word for it – take the IMF’s. In its own recently-released review of the Greek programme, it had this to say:
The program is fully financed through the first half of 2014, but a projected financing gap of €4bn will open up in the second half of 2014. Thus, under staff’s current projections, additional financing will need to be identified by the time of the next review, to keep the program fully financed on a 12-month forward basis, and the eurogroup has initiated discussions already on how to eliminate the projected 2014 gap.
In plain English, the IMF wants eurozone finance ministers to plug that gap, and do it quickly. Everyone may think that it will be easier in three-month’s time, since they will be past the all-consuming German national elections in September, but the IMF is urging eurozone officials to come up with an entirely new third bailout programme.

After all, not only does the EU have to plug the hole in 2014, but eurozone finance ministers have also agreed to extend the Greek programme through 2016 and haven’t provided any money for those final two years yet.

How much will be needed? According to this IMF chart in the same report, probably not all that much. In addition to the €4.6bn total price tag left to fill in 2014, it estimates another €6.5bn will be needed in 2015. By 2016, thanks to a growing primary budget surplus, Greece should be able to pay for itself, the IMF estimates.

The toughest thing here, as usual, will be the politics in the eurozone’s northern creditor countries. They have already committed to yet more debt relief for Greece sometime in the next six to 12 months – which will likely mean taking losses on their Greek bailout loans, already a combustible political issue – so agreeing to a third programme, even a small one, on top of that isn’t going to be easy.

At last week’s eurogroup news conference, EU economic chief Olli Rehn said he was looking forward to “a summer where we don’t have any Greek crisis.” He may get his wish, but the autumn could be far more difficult.


6/22/2013

IMF tells Greece - you've still got until July (Vid)


Πηγή: Reuters
June 21 2013

June 21 - David Lipton, the first managing director of the IMF, quashes media reports the fund will suspend Greek funding and says Athens has until July to come to an agreement on its bailout programme.


6/17/2013

Attac study says where rescue funds for Greece end up


Πηγή: DW
June 17 2013

The anti-globalization pressure group Attac has published a study indicating that the bulk of the rescue funds made available for Greece have tended to go to help banks. Ordinary people haven't profited much, it said.

More than three quarters of all rescue funds for Greece went directly to banks and rich investors, German daily newspaper "Süddeutsche Zeitung" claimed Monday, quoting a fresh study by the anti-capitalist pressure alliance Attac.

The group said out of the 207 billion euros ($276 billion) earmarked so far by international creditors, 160 billion euros ended up with Greek lenders and investors.

"Political elites have not been trying to rescue the Greek population, but the finance sector," said Lisa Mittendrein from Attac Austria.

According to the calculations made by the pressure group, the government in Athens put 58 billion euros into the domestic bank's recapitalization program. Another 55 billion euros were used to pay back sovereign bonds and 11 billion euros more to buy back accumulated debt.

Berlin not amused

Attac maintained an additional 35 billion euros were spent with a view to sweeten the 2012 debt reduction scheme also known as the Greek haircut for affected insurance companies and investment funds.

The group also said that only a small proportion of the money that actually did reach the Greek state budget could be used do anything meaningful for the population, as 35 billion euros had to be spent on debt servicing for the holders of sovereign bond bills.

"The widespread belief supported by European politicians that the various rescue packages for Greece have helped ordinary people in the country is no longer tenable," Mittendrein commented. Instead, she argued, Greeks have been made to foot the bill in terms of harsh austerity measures with all the known drastic social consequences like record-high unemployment.

The German government rejected the conclusions made by Attac, arguing that Greeks have profited from the government in Athens having more time to implement reforms. Berlin also claimed that all Greeks had profited from saving lenders from bankruptcy.


6/05/2013

IMF Admits Mistakes on Greece Bailout

A Greek flag flutters on above the parliament building as the moon rises over Athens, in a photo taken on May 23.

Πηγή: WSJ
By MATINA STEVIS
June 5 2013

BRUSSELS—The International Monetary Fund has admitted to major missteps over the past three years in its handling of the bailout of Greece, the first spark in a debt crisis that spread across Europe.

In an internal document marked "strictly confidential," the IMF said it badly underestimated the damage that its prescriptions of austerity would do to Greece's economy, which has been mired in recession for the last six years.

But the fund also stressed that the response to the crisis, coordinated with the European Union, bought time to limit the fallout for the rest of the 17-nation euro area.

The IMF said that it bent its own rules to make Greece's burgeoning debt seem sustainable and that, in retrospect, the country failed on three of the four IMF criteria to qualify for assistance.

The Washington-based fund released the document, prepared by IMF staff, on Wednesday after its contents were reported by The Wall Street Journal.

Over the last three years, a number of senior IMF figures, including Managing Director Christine Lagarde, have repeatedly said that the country's debt level was "sustainable"—likely to be repaid in full and on time.

Yet the document described the uncertainties around the Greek rescue as "so significant that staff was unable to vouch that public debt was sustainable with a high probability."

Two former IMF officials, speaking on condition of anonymity, said the fund's chief lawyer, Sean Hagan, repeatedly warned in mid-2010 that the Greek program was bordering on breaking the institution's rules.

"What happened at the time, and it's much easier with the benefit of hindsight, is that not all criteria of exceptional access as defined at the time were satisfied," Ms. Lagarde said in a separate interview last week.

"And yet there was a crying need at the time for support," she said. If the IMF hadn't tweaked its rules, "it probably would have meant no IMF support at that time."

The IMF report also said that it was too optimistic about the Greek government's prospects for a return to market financing and its political ability to implement the conditions of its rescue program.

An IMF spokesman declined to comment on the report, as did the Greek Finance Ministry and the European Commission.

The document is the most significant in a series of IMF analyses over the past few months that attempt to assess the institution's involvement in the euro-zone financial crisis.

The greater beneficiary of the 2010 bailout wasn't so much Greece as the wider euro-zone, the document suggested.

It described the rescue as a "holding operation" that "gave the euro area time to build a firewall to protect other vulnerable members and averted potentially severe effects on the global economy."

The IMF joined forces with the European Commission and the European Central Bank in 2010, forming the so-called troika, to manage Greece's first bailout of €110 billion ($143 billion)—one of the largest international rescues ever.

The three continued to run the country's second bailout, which came in 2012. Beyond Greece, the troika is managing the Irish, Portuguese and Cypriot bailouts.

While the fund has been scaling back its new financial commitments to euro-zone economies, it has put up a total of $47 billion for Greece, the biggest loan the IMF has ever made when compared with the size of a country's economy.

The fund criticized the delay restructuring Greece's massive debt load, which eventually came in May 2012. But it conceded that cutting it before then was "politically difficult" because of resistance from some euro-area countries whose banks held too much Greek government debt.

An immediate restructuring would have been cheaper for European taxpayers, as private-sector creditors were repaid in full for two years before 2012 using the money borrowed by Athens. Greece's debt level thus remained undented, but it was now owed to the IMF and euro-zone taxpayers instead of banks and hedge funds.

The IMF also said its own analysis of the future development of debt was wrong "by a large margin." The fund's debt-sustainability analysis—a critical piece of forecasting—"included stress tests but these turned out to be mild compared with actual outcomes."

The issue of the so-called fiscal multiplier—an estimate of how much an economy will contract for every euro in spending cuts or tax increases—has become part of the government's arsenal in its negotiations with the troika.

In talks next week, Greece will ask for permission to cut certain value-added, or sales taxes, arguing that an increase in restaurant taxes, for example, has generated less revenue not more by crimping spending.

Conversely a cut in the tax rate for eateries, the government says, could actually boost revenue by drawing in more diners. So far, however, officials at the European Commission have been cool to the idea.

The commission, which is the European Union's Brussels-based executive, comes in for special criticism in the IMF document.

The report says the commission "tended to draw up policy positions by consensus, had enjoyed limited success with implementing [fiscal conditions]…and had no experience with crisis management."

It adds that the commission focused more on "compliance with EU norms than on growth impact" and "wasn't able to contribute much to identifying growth enhancing structural reforms."

The commission is the lead EU institution tasked with designing and promoting growth-enhancing and job-creating policies for the entire bloc.

"None of the [troika] partners seemed to view the arrangement as ideal," the paper continued in a section discussing the "unusual" arrangement, noting that there were "marked differences of view within the troika, particularly with regard to the growth projections."

Those growth projections were wildly off the mark but Greece still had to meet the same targets of cutting deficit, it said. "The fiscal targets became even more ambitious once the downturn exceeded expectations. In addition, the starting point moved."

The paper added that the targets and the underlying macroeconomic projections weren't revised to reflect what was actually happening in Greece for 18 months, until December 2011.

The IMF had originally projected Greece would lose 5.5% of its economic output between 2009 and 2012. The country has lost 17% in real gross domestic output instead. The plan predicted a 15% unemployment rate in 2012. It was 25%.

Slowing the pace of austerity would have helped Greece's economy, but wasn't politically possible, the fund said.

"While earlier adjustment of the targets could have tempered the contraction, the program would have then required additional financing," which neither the IMF nor euro-area governments were prepared to give, the document said.

The paper criticized Greek governments for failing to implement structural economic changes that could have propped up the private sector and said the pain of the adjustment was "unevenly spread across society."

But it said there were few precedents for the size of the spending cuts and tax increases that Greece implemented to hit the targets.

The fund didn't explain why it made the choices it did in detail, nor why it agreed to troika analyses that it now says were incorrect. But it said IMF staff "explicitly flagged" risks in the Greek program implementation.

In last week's interview Ms. Lagarde said the review of the fund's experience in Greece "will probably lead us to reassessing the exceptions to the exceptional access criteria" and "will certainly lead us to calibrating well how we work with regional financing arrangements."


4/20/2013

Schaeuble wants investors involved in future bailouts: report


By Reuters
April 20 2013

BERLIN: Germany's finance minister said investors must be involved in future bank rescues in crisis states but added Cyprus, where a bailout is imposing losses on depositors, was still a unique case, a German magazine reported on Saturday.

Asked whether the charge on depositors in Cypriot banks was a one-off case, Schaeuble said: "The involvement of owners, bondholders and uninsured depositors has to be the norm if a financial institution runs into trouble," according to Wirtschaftswoche.

"Otherwise we will never get a grip on the moral hazard problem whereby banks which do risky business make big profits but then burden the general public with their losses when they fail," he was quoted as saying.

"That cannot be allowed."Last month Dutch Finance Minister Jeroen Dijsselbloem, who heads the Eurogroup of euro zone finance ministers, said Cyprus' rescue programme represented a new template for resolving euro zone banking problems and other countries may have to restructure their banking sectors.

His comments unnerved markets and he later put out a statement that Cyprus was a specific case, that plans were tailor-made for each situation and no models or templates were used.

Schaeuble was quoted as saying Dijsselbloem had been unfairly pilloried for his comments.

"But he said Cyprus could be a 'template' for the future. Financial markets misunderstood that, thinking there was a risk of Cyprus happening elsewhere. But that is not the case because Cyprus is a very unique case."

Cyprus and international lenders decided that depositors who had more than 100,000 euros in the two biggest Cypriot banks would lose some of their money to contribute to the recapitalization of the institutions, along with shareholders and bondholders.

Earlier this week a European Commission document showed they stood to lose up to 8.3 billion euros through the restructuring of the two institutions.

Schaeuble said Cyprus would get 10 billion euros in aid, adding that it would not get any more because otherwise the island's debt sustainability would not be guaranteed.


4/03/2013

What Happens to Cyprus’s Natural Gas with the Current Bailout Plan?


Πηγή: Oilprice
By James Burgess
April 2 2013

Where does the Cyprus bailout deal leave its energy reserves?

It has been estimated over the years that the southeastern waters of Cyprus contain 50 to 60 trillion cubic feet of natural gas and 1.7 billion barrels of crude oil, worth around $400 billion.

The government in Nicosia has always based plans for the future on this projected income, so the idea of raising money based on future natural gas revenues as a means to alleviate some of the pressure caused by the immense debt that the island nation found itself in, was out of the question.

Natural gas production is not expected until around 2018 or 2019, and Cyprus refused to use any discounted future valuations to raise money in the present, not wishing to run the risk of selling their future for far less than it might be worth.

After the first bailout plan offered by the EU was rejected, however, a viable option that was considered was to accept direct financial assistance from Russia in return for the rights to explore and develop Cyprus’s natural gas.

This worried the EU who had, for a long time, been hoping that Cyprus’s natural gas would offer genuine relief from an almost complete reliance on Russian exports.

Luckily the deal with Russia never really materialised, and, possibly motivated by the fear that Russia could get hold of the gas reserves, Europe was able to agree a deal with Cyprus, leaving all natural gas reserves completely untouched.

Unfortunately analysts are predicting that this bailout plan will be just the first step on the road to recovery, and the security of the natural gas reserves may be threatened again in the future as Nicosia looks for other methods to raise capital.


3/23/2013

As Cyprus Implodes, Bitcoin Interest Explodes


Πηγή: Fox Business
By Matt Egan
March 22 2013

As policymakers in Europe threaten the sanctity of bank deposits in crumbling Cyprus, the faceless operators of decentralized electronic currency Bitcoin must be smiling somewhere.

The currency, a favorite among those worried about the safety of traditional banking and paper currency, is emerging as an apparent winner from the drama surrounding the bailout of tiny Cyprus.

Bitcoin “is clearly having a breakthrough moment here, and a deeply surprising one given its novelty and nascent infrastructure,” said Nicholas Colas, chief market strategist at ConvergEx, in a note on Friday.

To be sure, Bitcoin is still a relatively new and small system that is subject to technical glitches and regulators are only now scrambling to keep up. Still, led by surging interest in the embattled eurozone and Russia (a favorite client of Cypriot banks), that breakthrough is clear through a number of metrics, including the surging value of the currency itself.

One Bitcoin is now worth around $73.75, up 84% from just two weeks ago when it was worth around $40.

Not Your Father’s Currency

The value of Bitcoins outstanding has now exploded beyond $800 million. Colas notes that if Bitcoin were a country, its outstanding currency would rival the annual gross domestic product of a dozen World Bank-recognized nations.

People “are looking for alternatives” because of a “loss of confidence in paper money and traditional banking systems,” said Jim Rickards, author of Currency Wars.


So what are Bitcoins and why are they enjoying a moment in the spotlight now?

Founded in 2009 as an open-source software code, Bitcoin is a complex and anonymous type of electronic currency that can be swapped for local currencies like dollars, yen and euros.

Users can create accounts, deposit local currency and then use that cash to buy Bitcoins at a rate that fluctuates with the market. The Bitcoins can be stored in an online wallet, used to make purchases and converted back into local currencies.

However, unlike most currencies that are controlled by central bankers, Bitcoin is highly decentralized and the number of Bitcoins in circulation expands at a predictable and limited rate. Bitcoin also notes that its accounts cannot be seized by local authorities.

Crisis in Cyprus Buoys Bitcoin

For all of these reasons, Bitcoins stand in stark contrast with the value of euros sitting in Cypriot banks.

The controversial push to impose a levy on bank deposits in Cyprus, a tax haven and money laundering epicenter favored by Russians, has fueled ATM cash shortages and forced the tiny island country to shut its banks for a week.

The decision to go after bank deposits reflects the lack of options to raise money for a bailout of Cyprus and its outsized banking system. However, that move also appears to have broken a cardinal rule in financial crises: don’t give people a reason to fear for the safety of their bank accounts.

“Cyprus, if it’s not Lehman Brothers, it’s certainly causing a certain amount of nervousness,” said Rickards, a partner at New York hedge fund JAC Capital Advisors.

Colas said he’s been seeing “explosive growth” in the Russian ruble/Bitcoin exchange in recent days. He said average daily transactions have soared from around 500,000 to 1 million rubles per day to 3 million to 3.5 million rubles a day on Wednesday and Thursday.

“It may not seem fair, but the deposits of oligarchs, drug dealers and tax cheats need to have the same protection as widows and orphans,” said Colas. “The people themselves, no. But if you can’t convict them for their crimes, attacking everyone’s deposits in retribution is bad policy.”

Rickards said the recent popularity of Bitcoins is part of a broader trend around the world in favor of alternative currencies.

U.S. Treasury Takes Note

This includes in the U.S., as some fear the Federal Reserve’s unprecedented quantitative easing program, which has swelled the central bank’s balance sheet to $3 trillion, may eventually cause rampant inflation.

“Gold is a great way to preserve wealth, but it is hard to move around,” said Rickards. “You do need some kind of alternative and Bitcoin fits the bill. I’m not surprised to see that happening.”

Regulators seem to be taking notice as earlier this week the Treasury Department said it is applying money-laundering rules to so-called virtual currencies.

“It’s almost a badge of respect when the Treasury starts regulating you,” said Rickards. “You must be doing something right.”

The attention from the U.S. comes amid some concern that Bitcoins and similar virtual currencies could become a haven for criminal activity. An FBI report last year revealed that at least one online service accepts Bitcoins in exchange for illegal drugs.

“It’s not a knock on Bitcoin,” said Rickards. “I’m sure there are criminals using the Bitcoin world, but there are criminals and bad actors in the dollar world as well. The sight of a drug smuggler opening a suitcase full of $100 bills is not unusual.”

‘Cautionary Tale’

It’s also worth pointing out that while Bitcoin may not be subject to policy missteps like the Cyprus deposit proposal, the electronic exchange isn’t immune to technical issues.

An apparent glitch in the Bitcoin network fueled a steep selloff earlier on March 12 that caused the currency’s value to briefly plummet 23% to $37 before recovering. Interestingly, the snafu doesn’t appear to have dented demand for Bitcoins as the currency’s value has rebounded well beyond $70 since then.

So what does the rise of virtual currency say about the state of confidence in the traditional banking structure?

“The rampant success of Bitcoin is a profoundly cautionary tale for global monetary systems. And we seem to be more in the introduction rather than the epilogue of the story,” said Colas. “If central banks and regulators actually ran their monetary policies to maintain public confidence in the value of their currency, Bitcoin wouldn’t have a chance. “


3/19/2013

A much better alternative for Cyprus


Πηγή: Reuters
By Felix Salmon
March 19 2013

Andrew Ross Sorkin defends the Cyprus deal today, on the grounds that (a) Cyprus is “tiny”, and “largely irrelevant to the global economy”; (b) Cyprus is a genuinely unique case; (c) it would be grossly unfair not to bail in Russian depositors, who are generally losing less than they’ve made in interest over the past few years; and (d) the Greek alternative “will not work in Cyprus”, and that therefore (this last bit is only implied, never stated outright) the current plan is really the only option.

Notably, Sorkin doesn’t attempt to defend the most indefensible part of the plan — the confiscation of wealth from depositors with sovereign deposit guarantees. While hedge-fund bondholders will get paid their full $1.4 billion on June 3, the date of Cyprus’s next coupon payment, small depositors with just a few hundred or a few thousand euros in savings will lose money which the Cypriot government had promised them was safe. Why is the government’s promise to foreign hedge funds more important than its promise to its own citizens? Sorkin never attempts an answer to that one.

And even if Cyprus is tiny and irrelevant to Andrew Ross Sorkin, it most certainly isn’t tiny and irrelevant to the hundreds of thousands of people who live there, and deserve for their government to deliver the best possible plan it can.

Which raises the single biggest question facing the Cypriot parliament as it prepares to vote today: should it accept the deal on the table, or should it hold out for something better? And if it chooses the latter option — as seems likely — should it simply fiddle with the tax-rate percentages, much as one might fiddle with the Breakingviews Cyprus calculator, or should it try to build something which is more different and more fair? Most importantly, what alternatives does Cyprus’s parliament have?

This is where Sorkin’s column is (at least in its implication) wrong: there is an alternative. It isclearly better, in every regard, than the option currently on the table. And it most emphatically isworkable. We know that it’s workable because it has been put forward by none other than Lee Buchheit, the godfather of sovereign debt restructuring, and for decades, in dozens of sovereign contexts, every time that Lee Buchheit has said something can be done, he’s been absolutely right.

Here’s the short, three-page paper: it’s called Walking Back from Cyprus, and it’s authored by Buchheit and his frequent collaborator, Mitu Gulati of Duke University. Their plan is simple:

First, leave all deposits under €100,000 untouched. Hitting those deposits was by far the biggest mistake of the Cyprus plan as originally envisaged, and everybody would be extremely happy if guaranteed depositors could be kept whole.

Second, term out everybody else by five years, or ten if they prefer.

That’s it! That’s the whole plan, and it’s kinda genius. If you have bank deposits of more than €100,000, they will be converted into bank CDs, with a maturity of either five years or 10 years — your choice. If you pick the longer maturity, then your CD will be secured by future Cypriot gas revenues, which could amount to hundreds of billions of dollars.

And if you have sovereign bonds, they too will be termed out by five years, giving Cyprus a bit of breathing room to get its act together.

Do that, say Buchheit and Gulati, and you manage to reduce the size of the needed bailout bymore than the €5.8 billion that Cyprus is currently planning to raise with its tax on bank deposits — and you don’t touch anybody’s principal at all. To be sure, the new CDs, which would be tradable, would surely trade at less than par: there would be a present-value haircut on deposits over €100,000. But that’s going to happen anyway. And at least in this case patient depositors will have a chance of getting all their money back in full — with interest. And, most importantly, guaranteed depositors will remain unscathed.

This is the deal that no one had the imagination to put on the table during all-night negotiations last week, and it makes a lot more sense than what we’re looking at right now. In the first round of negotiations, the Germans had the upper hand, presenting Cyprus with a take-it-or-leave-it deal. Buchheit and Gulati have now given the Cypriot parliament the opportunity to turn the tables: pass a bill along these lines, and tell the Germans to take it or leave it.

The Buchheit/Gulati plan would cost Germany no more than the current plan, so the Germans would have no good reason to veto. But if the Germans did veto, then the result would be a sovereign nation being forced to exit the Eurozone: the worst possible outcome of all. Given that kind of ultimatum, I suspect the Germans would sign on to the Cypriot plan.

The ball is in the Cypriot parliament’s court today, and most observers are expecting the current plan to go through, with a tweak here or there to the tax rates and the points at which they kick in. But Buchheit and Gulati have now given Cyprus’s parliament a clear Plan B. If the lawmakers want to reject the Eurogroup’s plan, they know what they must do.


Cyprus parliament to veto deposit tax

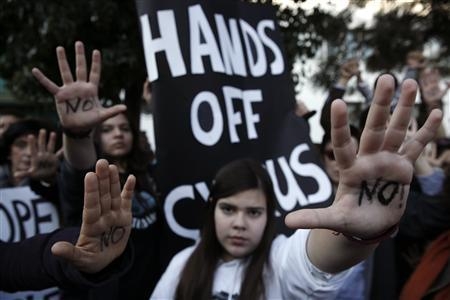
Protesters raise their open palms showing the word ''No'' during an anti-bailout rally outside the parliament in Nicosia March 18, 2013.

Πηγή: Reuters
By Michele Kambas and Karolina Tagaris
March 19 2013

Cyprus's parliament was set to reject a divisive tax on bank deposits in a vote on Tuesday, pushing the island closer to a debt default and banking collapse.

A weekend announcement that Cyprus would break with previous practice and impose a levy on bank accounts as part of a 10 billion euro ($13 billion) EU bailout prompted turmoil on European financial markets on Monday.

Cypriot and euro zone officials have sought to soften the initially proposed levy of 6.75 percent on depositors of up to 100,000 euros and 9.9 percent above 100,000 to ease the burden on small savers.

But passage of the bill in the 56-member chamber, where no party has a majority, was unlikely. The House of Representatives was expected to meet at 1600 GMT(12:00 EST).

"It looks like it won't pass," Cypriot government spokesman Christos Stylianides told state radio.

Tuesday's vote, originally planned for Sunday, has been postponed twice already. Three parties have said outright they will not support the tax, while a fourth, in the co-governing coalition, said it cannot support it as it stands either.

Cypriot President Nicos Anastasiades asked the EU for more aid during a telephone conversation with German Chancellor Angela Merkel on Monday, with a second call likely on Tuesday. Stylianides said Anastasiades may also speak to Vladimir Putin, the Russian president.

The tax will batter not only Cypriots, but thousands of Europeans and Russians with business interests on the island. Putin on Monday described it as "unfair, unprofessional and dangerous."

Cypriot finance minister Michael Sarris was due to hold meetings in Moscow on Wednesday.

Stunned islanders emptied cash machines over the weekend and banks are to remain shut on Tuesday and Wednesday to avoid a bank run. Hundreds of protesters rallied outside parliament on Monday, honking horns and holding banners saying "We are not your guinea pigs!"

"If they vote for this tax they will face the fury of the people," said Markos Economou, a 47-year-old physics teacher and father of two. "The banks and the politicians should pay for this mess, not the people."

ONE-OFF?

Seeking to overcome divisions within the government's own ranks, ministers were scrambling on Monday to ease the pain for small savers by tilting more of the tax towards those with deposits greater than 100,000 euros.

Euro zone finance ministers were in favor of imposing a 15.6 percent levy on deposits of above 100,000 euros to help recapitalize Cyprus' financial sector while sparing depositors up to that level, officials told Reuters.

It was not clear what version of the levy would eventually be voted on in Cyprus. The government maintains that Cyprus has no choice but to accept the bailout with the levy, or go bankrupt.

While Brussels has emphasized that the measure is a one-off for a country that accounts for just 0.2 percent of European output, fears have grown that savers in other, larger European countries will be spurred to withdraw funds.

"If you're a small depositor in Cyprus you'll tell yourself that it would have been better to keep your money under the carpet than in a bank," said a French bank executive who declined to be named.

"And if you're a Greek, a Spaniard or an Italian, well, you'll tell yourself that you might be next."


The Cyprus experiment and the legitimisation of money laundering


Πηγή: New Europe
By CHRISTOS KISSAS
March 17 2013

Since saving Dexia, the troubled Franco-Belgian bank, costing around €100 billion, the benefit from a 10% levy on Cyprus banks’ deposits, amounting to less than €6 billion, sounds rather limited, compared to the potential risks of destabilising the whole banking system of Southern European eurozone countries.

This leads us to believe that this decision was rather political than economic. On one hand, it sets a precedent, breaking the taboo of bank deposits’ inviolability in a European country; on the other hand, it strikes a decisive blow on Cyprus’ status as a tax haven.

The emphasis, for this decision, was put on moral grounds: it was considered unacceptable for an EU member state to be a low-tax jurisdiction and to facilitate tax evasion. But is Cyprus the only case?

As a matter of fact, over the last few years, we are witnessing a hysteric aggressiveness of many OECD and EU institutions against countries considered to be ‘tax havens’, based on the the ‘moral’ grounds of fighting tax evasion and money laundering. If these stated purposes were the only ones, there would be no reason not to support this action.

However, there are strong indications that the tax haven ‘holy war’ has a hidden agenda, that of channeling most transactions in a small number of traditional financial centres.

When speaking about tax havens, it is useful to remember that the term is extremely large, and as many as fifty countries, including several EU members and the US, in some ways act as a tax shelter for international money. To give an example, both Ireland and the Netherlands are excellent places to set up a holding structure and to divert profits made from sales in other European countries. For Ireland, going under a bailout didn’t compromise its tax haven status.

Then, comes London, the world’s prime offshore centre. A specialty of London is a structure known as LLP, or Limited Liability Partnership, a tax transparent partnership heavily used in international trade. In fact, it’s a three-stage structure, comprising the LLP itself, its shareholders (usually “pure” offshore companies, such as BVI international business companies), and its subsidiary, for example a Russian or Ukrainian company, depending on the place of trade.

These LLP’s are among the main instruments of worldwide transfer pricing, resulting in billions of euros in tax losses for third countries…

If we enlarge the scope of the analysis, and look beyond the EU, we must admit that the United States themselves are in some respect an excellent tax haven.

Some States, such as Delaware and Montana made a specialty of setting up quickly and relatively anonymously so-called Limited Liability Companies (LLC’s), which are zero-tax structures if their owners are non-US residents and their activity is exclusively carried outside of the United States.

A recent study by Professor Michael Findley of the University of Texas at Austin et al. has even concluded: “It is easier to obtain an untraceable shell company from incorporation services (not law firms) in the United States than in any other country save Kenya.”

In this context, isn’t it really hypocritical for the Eurogroup to only ‘teach Cyprus a lesson’? Many think it is, and some even relate this ‘lesson’ to the fact that a large part of funds deposited in Cyprus’ banks (around €20 billion) are from Russia.

Total funds parked in tax havens are estimated at €20 trillion by ‘The Economist,’ and between €20 and €30 trillion by the non-government organisation ‘Tax Justice Network;’ the obvious question is: why is “morality” only applied to Cyprus, which only accounts for 1% of such funds?

Christos Kissas, PhD

www.christoskissas.com


The View From Greece On "The Hypocrisy Of Leaders" And Why "There Is A More Insidious Infection That Could Spread"


Πηγή: Zerohedge
By Tyler Durden
March 18 2013

The Eurogroup’s decision on Friday to impose a one-off tax on depositors in Cyprus may mark a turning point in the euro crisis. Only, the single currency’s decision makers might soon realize that in taking this particular turn, they also ran out of road.

Under pressure from several members of the eurozone – Germany in particular, if reports are accurate – the new Nicosia government agreed that deposits above 100,000 euros would be taxed 9.9 percent and those under 100,000 at a rate of 6.75 percent.

This is an unprecedented decision for a eurozone country. It is also one whose potential consequences reach much further than an island in the eastern Mediterranean. It threatens to cause the transmission system between the economic and financial sectors on one side and the political and social on the other to seize up. Without this, the euro cannot be propelled forward. It cannot function.

The choice to tax depositors has prompted an intense economic debate about whether it was the correct policy or not. Both sides have put forward points worth considering. Those arguing against the decision have pointed, for instance, to the risk of contagion in other eurozone countries that are facing economic problems. Those who defend the Eurogroup’s stance say depositors in Cyprus earned high interest, which gave them profits over the last few years and carried a bigger risk.

Setting these arguments aside, the eurozone ignores at its peril the fact that these decisions do not happen in an economic or financial vacuum. They have political and social consequences that cannot be ignored if the single currency is to have a future. One need only look at the political changes that have taken place in Greece, Ireland, Portugal, Spain, Italy and elsewhere to realize that the euro area is running out of leaders who have the backing needed to implement the decisions being taken.

Cypriot President Nicos Anastasiades, elected just last month, has to clarify to his people why he is adopting a bank deposit tax when he told voters a few weeks ago that he was absolutely opposed to it. Even before Anastasiades had returned from Brussels, his political opponents were demanding a referendum on the deposit tax. Some were even calling for new elections or an exit from the euro.

Anastasiades also has to explain to Cypriots why small-time depositors have to pay a similar levy to the one some eurozone countries supposedly demanded so alleged Russian oligarchs would be forced to pay for bailing out the island’s banking system. Furthermore, he has to inform them why the Cypriot government’s pledge to guarantee deposits up to 100,000 euros - supposedly even in the most extreme circumstances - is not even worth the paper it was written on.

The implications for people’s trust in their government and financial system are obvious. It would be remiss to think that this wariness will be contained just to Cyprus. While many will be watching next week for signs of financial contagion from the Cypriot decision in other parts of the eurozone, with Spaniards or Italians possibly withdrawing savings from their banks, there is a more insidious infection that could spread.

Cypriots will be given equity in their banks in return for the tax but what value will this have when they no longer have faith in the banking system? Cypriots will be told that the deposit tax will stave off further measures but they only have to look to Greece or Portugal to see that promises of no more taxes or cuts have little value. They will be told that there was no alternative but then they will hear about pressure from other single currency members and concerns about the upcoming German elections.

And, all the time, citizens in other troubled eurozone countries will watch and grow warier. They will interpret the policies advocated by the stronger members as punitive for the weaker. They will consider the hypocrisy of leaders who cry foul about money laundering in Cyprus but turn a blind eye if it is happening in Lichtenstein, Switzerland, Luxembourg, the City of London or anywhere else in Europe. They will realize that their government’s promises carry no value when measured against the ideas, motives or obsessions of the single currency’s big players.

This is the point at which the political and social sectors will experience a complete disconnect from the economic and financial. Restoring the connection will be an immense task.

Then, these same citizens will begin to ask themselves where their interests lie, what’s in the euro for them and whether other options would be better. And, as they are mulling over these thoughts, they will look to other parts of Europe and see people like them but also analysts and policy makers wondering what all the fuss is about. They will hear others who have not had to suffer any hardship or financial losses wonder why there is such a negative reaction to wages being slashed, taxes being hiked or deposits being taxed.

This is the point at which the links within the eurozone will begin to pop apart, when citizens will turn to Beppe Grillo-style solutions, to nationalists, extremists or to anyone who promises a different path.

This is the point at which the vehicle stops functioning and the road ends.